
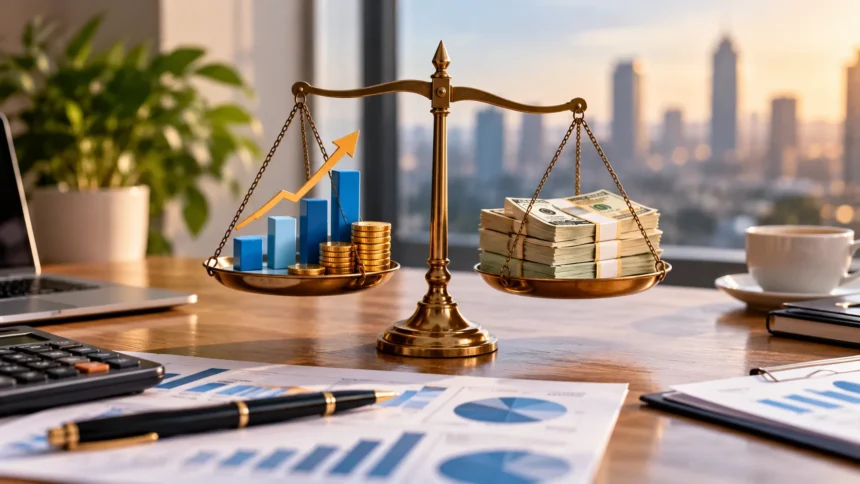
A business can report impressive profits and still struggle to pay its bills. This situation often confuses business owners who assume that earning money automatically means having enough cash available. Understanding why profit and cash are not the same thing is essential for maintaining financial stability, managing daily expenses, and making informed business decisions that support sustainable growth.
Profit measures how much a business earns after accounting for its expenses, while cash represents the money available to make payments. These two financial measures are connected, but they do not always move in the same direction. A company may generate strong sales without receiving customer payments immediately, creating a gap between reported earnings and available funds.
Recognizing the difference between profit and cash flow helps business owners avoid financial surprises and improve operational planning. It also explains why profitable companies sometimes experience financial difficulties despite reporting positive results. This guide explores the relationship between profitability and liquidity, common cash flow challenges, financial statements, and practical strategies for managing business finances effectively.
What Is Profit in Business?
Profit is the financial amount remaining after a business subtracts its recognized expenses from its revenue. It measures whether business activities generate more income than the costs associated with delivering products or services. Profitability is commonly used to evaluate business performance, operational efficiency, and the long-term financial sustainability of an organization.
There are several types of profit, including gross profit, operating profit, and net profit. Gross profit represents revenue minus the direct costs of producing goods or delivering services. Operating profit accounts for additional operating expenses, while net profit generally reflects the remaining earnings after applicable expenses, interest, and taxes are considered.
A profitable business demonstrates that its recognized revenue exceeds its recognized expenses over a particular accounting period. However, this does not necessarily mean the company has received all its customer payments. Accounting methods, payment schedules, and financial obligations can create significant differences between reported profits and the amount of money available in the bank.
What Is Cash Flow and Why Does It Matter?
Cash flow refers to the movement of money into and out of a business during a specific period. Cash inflows may include customer payments, loan proceeds, and funds received from selling assets. Cash outflows include employee salaries, supplier payments, rent, taxes, loan repayments, and purchases required to maintain daily operations.
Positive cash flow occurs when more cash enters the business than leaves during the measured period. Negative cash flow means outgoing payments exceed incoming funds. Neither condition tells the entire story of profitability because financing activities, investment decisions, and payment timing can significantly influence cash movements.
Cash flow matters because businesses must use actual available funds to meet financial obligations. Even companies with strong sales and healthy profit margins can experience difficulties when customers pay slowly or large expenses become due. Monitoring cash flow helps organizations maintain liquidity and prepare for expected financial commitments.
Why Profit and Cash Are Not the Same Thing
The main difference between profit and cash involves accounting recognition and the timing of financial transactions. Profit reflects revenue and expenses recorded under applicable accounting rules. Cash flow measures actual movements of money, meaning financial performance and available funds can differ significantly during the same reporting period.
Under accrual accounting, businesses generally recognize revenue when it is earned rather than when customers make payments. Expenses are similarly recognized according to accounting principles instead of simply when cash leaves the bank. This approach provides useful information about financial performance but does not directly show whether enough cash is available for immediate obligations.
Cash flow statements address this distinction by tracking money received and paid through operating, investing, and financing activities. A company may report positive net income while experiencing negative operating cash flow because customer payments remain outstanding. Understanding both measures provides a more complete picture of business health than examining profit alone.
A Simple Example of Profit vs. Cash Flow
Imagine a consulting company completes $20,000 worth of services during one month and records $12,000 in related expenses. Under accrual accounting, assuming all relevant revenue and expenses are recognized in that period, the company reports an $8,000 profit. This calculation suggests that its business activities generated a positive financial result.
However, suppose customers have paid only $5,000 by the end of the month. If the company has already paid $10,000 of its expenses, its operating cash movement from these transactions is negative $5,000. The remaining customer payments are recorded as accounts receivable rather than money immediately available for spending.
This example demonstrates how a business can appear profitable while facing short-term cash shortages. The company has earned revenue, but much of the money has not yet arrived. Without sufficient existing cash reserves or other funding, it may struggle to cover upcoming expenses despite reporting positive accounting earnings.
How Accrual Accounting Creates Differences
Accrual accounting records business transactions when economic activities occur, subject to applicable recognition rules. Revenue is generally recognized when goods or services are provided, while expenses are recorded according to the relevant accounting period. This method helps businesses evaluate profitability without depending entirely on the timing of customer payments.
For example, a company may deliver products in December but receive payment in January. Under accrual accounting, the associated revenue may appear in December’s income statement, while the cash receipt occurs in January. This timing difference creates a temporary separation between reported profit and cash flow.
The same principle applies to certain expenses. A business might receive supplies and record an expense or inventory asset before paying the supplier. Understanding these accounting differences helps managers interpret financial statements accurately and avoid assuming that every recorded transaction immediately changes the bank balance.
How Accounts Receivable Affect Cash Flow
Accounts receivable represents amounts customers owe a business for goods or services provided on credit. These balances may contribute to recognized revenue and profit before the business receives payment. When receivables grow faster than customer collections, a company can report increasing sales while experiencing pressure on its available cash.
Delayed customer payments create practical challenges because business expenses often continue regardless of collection schedules. Employees expect salaries, suppliers require payment, and operating costs remain due. A company with substantial outstanding invoices may therefore need additional working capital to support operations while waiting for customers to pay.
Managing accounts receivable effectively involves clear payment terms, accurate invoicing, and consistent communication with customers. Businesses can monitor overdue invoices and review collection patterns to identify emerging problems. Improving collection efficiency helps convert earned revenue into usable cash without necessarily changing the amount of profit recognized.
How Inventory Can Reduce Available Cash
Inventory represents products or materials a business purchases or produces for future sales. Buying inventory requires cash or creates supplier obligations, but the purchase does not always become an immediate expense on the income statement. Under typical inventory accounting, costs are recognized as goods are sold rather than when inventory is acquired.
This difference becomes important when businesses purchase large quantities of products before receiving customer orders. Cash may be tied up in unsold inventory for weeks or months. The company could still report strong profitability from previous sales while having limited funds available for new expenses.
Effective inventory management helps businesses balance product availability with financial flexibility. Forecasting demand, monitoring stock turnover, and avoiding unnecessary purchases can reduce the amount of cash tied up in goods. Better inventory planning supports liquidity while helping companies maintain appropriate stock levels for customer demand.
Why Loan Repayments Affect Cash but Not Profit Equally
Business loans create another important difference between profit and cash flow. When a company receives loan proceeds, its cash balance increases, but the borrowed amount is not treated as ordinary business revenue. The money must eventually be repaid, meaning the initial increase in cash does not represent an increase in profitability.
Loan repayments generally include principal and interest. Interest expense affects reported profit according to applicable accounting rules, while repayment of the principal reduces the outstanding liability rather than appearing as an expense on the income statement. Both types of payment can reduce available cash, even though their accounting treatment differs.
This distinction explains why a profitable company may struggle with debt obligations. Strong earnings do not guarantee that cash receipts will align with scheduled repayments. Monitoring debt maturity dates, financing costs, and available cash reserves helps businesses prepare for these commitments without confusing borrowed funds with earned income.
How Equipment Purchases Create Cash Flow Differences
Businesses frequently purchase equipment, vehicles, computers, and machinery to support operations or expansion. These investments may require substantial cash payments when acquired. However, under accrual accounting, qualifying long-term assets are generally recorded on the balance sheet rather than treated entirely as immediate operating expenses.
The cost of these assets is often allocated across their useful lives through depreciation. Depreciation reduces accounting profit over time without requiring a new cash payment each time the expense is recognized. The original equipment purchase, meanwhile, may create a significant cash outflow during the acquisition period.
Understanding this difference is especially important for businesses investing in new infrastructure. A company may report healthy profits while its cash balance declines because of major equipment purchases. Reviewing capital expenditure plans alongside operating cash flow helps managers determine whether growth investments remain financially manageable.
Can a Profitable Business Run Out of Cash?
Yes, a profitable business can run out of cash when incoming payments do not arrive quickly enough to cover financial obligations. Profitability reflects financial performance over an accounting period, while liquidity determines whether the business can make payments when required. These two conditions must be monitored separately to understand operational financial health.
Rapid growth can make this problem particularly noticeable. A company may accept larger orders, hire additional employees, and purchase more materials before collecting payment from customers. Revenue and profit may increase, but the business may require substantial working capital to finance the additional activity.
Unexpected expenses can create further pressure on available funds. Equipment repairs, delayed customer payments, seasonal changes, or large tax obligations may reduce liquidity. Maintaining cash reserves and preparing realistic cash flow forecasts helps businesses manage these risks even when their income statements indicate positive profitability.
Can a Business Have Cash Without Making a Profit?
A business can have substantial cash available while reporting an accounting loss. This may happen when owners contribute additional capital, the company receives financing, or it sells existing assets. These transactions can increase available funds without necessarily creating operating profit or improving the underlying performance of the business.
For example, a company might receive a $100,000 loan while reporting a $15,000 operating loss. Its bank balance could increase despite the negative financial result. However, the loan creates a repayment obligation, so the additional cash should not be confused with sustainable earnings from normal operations.
Businesses may also generate positive operating cash flow during a loss-making period because of noncash expenses or working capital changes. This situation demonstrates why financial analysis requires more than checking the bank balance. Understanding the sources of cash helps managers distinguish temporary funding from reliable operating performance.
How to Read Profit and Cash Flow Statements
The income statement summarizes revenue, expenses, and profit over a particular reporting period. It helps business owners evaluate margins, operating efficiency, and overall earnings. However, it does not provide a complete explanation of when customers pay or when financial obligations require cash settlement.
The cash flow statement explains how cash changes through operating, investing, and financing activities. Operating cash flow reflects cash generated or used by normal business activities. Investing cash flow generally includes purchases and sales of long-term assets, while financing cash flow records transactions such as borrowings, debt repayments, and owner distributions.
The balance sheet provides additional context by showing assets, liabilities, and equity at a specific date. Accounts receivable, inventory, cash balances, and outstanding loans help explain differences between earnings and liquidity. Reviewing all three statements together supports a more accurate understanding of financial performance and the company’s ability to meet obligations.
Practical Ways to Improve Business Cash Flow
Improving cash flow often begins with managing the timing of incoming and outgoing payments. Clear customer payment terms, prompt invoicing, and regular collection follow-ups can reduce unnecessary delays. Businesses should also maintain accurate records of expected receipts and upcoming expenses to identify potential shortages before they affect daily operations.
Cost management and inventory planning can also strengthen financial flexibility. Reviewing recurring subscriptions, supplier arrangements, and unnecessary purchases helps identify avoidable spending. Maintaining appropriate inventory levels reduces cash tied up in unsold products while supporting reliable customer service and normal business operations.
Creating a cash flow forecast provides another important benefit. A forecast estimates expected cash receipts, payments, and future balances over a defined period. Regularly updating these projections allows business owners to plan major purchases, prepare for seasonal changes, and make more informed decisions about financing requirements.
Why Working Capital Matters for Business Stability
Working capital is commonly calculated by subtracting current liabilities from current assets. It provides an indication of the short-term resources available to support business obligations. Components such as cash, accounts receivable, inventory, and supplier payables influence working capital and help explain operational liquidity.
Positive working capital often suggests that current assets exceed current liabilities, but this does not guarantee immediate payment capacity. Inventory may take time to sell, and customers may delay settling invoices. Businesses should therefore consider the quality and accessibility of current assets rather than relying entirely on the working capital figure.
Effective working capital management involves balancing customer collections, inventory purchases, and supplier payments. Businesses benefit when cash moves efficiently through the operating cycle. Monitoring working capital alongside cash flow forecasts helps managers identify financial pressure and improve the coordination of everyday business transactions.
Common Mistakes Businesses Make About Profit and Cash
One common mistake is assuming that a positive net profit automatically means enough money is available for spending. Business owners may approve large purchases or additional expenses without checking upcoming payment obligations. This misunderstanding can create financial stress when customer receipts arrive later than expected or cash is already committed elsewhere.
Another mistake involves treating borrowed funds as business earnings. Loans and owner investments can increase the bank balance, but they do not demonstrate that operations are profitable. Companies that depend heavily on financing without improving their operating performance may face growing debt obligations and long-term financial difficulties.
Failing to monitor cash flow regularly is another significant problem. Reviewing profitability only at the end of a reporting period may leave important liquidity issues unnoticed. Businesses should maintain accurate financial records, examine payment schedules, and monitor relevant cash flow indicators to support consistent financial decision-making.
Conclusion
Understanding why profit and cash are not the same thing is essential for making responsible business decisions. Profit measures financial performance after recognizing revenue and expenses, while cash flow tracks actual movements of money. These measures provide different but equally important insights into a company’s financial condition and long-term sustainability.
A business can earn a profit while experiencing cash shortages because of delayed customer payments, inventory investments, equipment purchases, or debt repayments. Similarly, a company may hold substantial cash without generating profitable operations. Recognizing these differences helps business owners interpret financial reports more accurately and avoid potentially costly assumptions.
Strong financial management requires monitoring profitability, liquidity, working capital, and future payment obligations together. Accurate financial statements, realistic cash flow forecasts, and effective collection practices can support more stable operations. By managing both profit and cash carefully, businesses can improve financial resilience and make better decisions about sustainable growth.
Frequently Asked Questions
What is the main difference between profit and cash flow?
Profit represents revenue minus recognized expenses during an accounting period. Cash flow measures actual money entering and leaving a business, including payments that may not directly affect current profit.
Can a business be profitable but have no cash?
Yes. A business can report positive profits while experiencing cash shortages because customers have not paid, inventory purchases require funding, or significant financial obligations become due.
Why is cash flow important even when a business makes a profit?
Cash flow determines whether a business can pay employees, suppliers, rent, taxes, and other obligations on time. Profitability alone does not guarantee sufficient funds are available for these payments.
Can a company have positive cash flow and negative profit?
Yes. Loans, owner investments, asset sales, noncash expenses, and working capital changes can contribute to positive cash flow even when a company reports an accounting loss.
Which is more important for a business, profit or cash?
Both are essential. Profit helps measure long-term financial performance, while cash supports immediate operations and payment obligations. A financially healthy business generally needs sustainable profitability and effective cash management.